
Learning how to use equity to buy a property is the moment most Australian investors stop being stuck. You do not always need fresh savings, because the deposit may already exist inside your current home. This guide explains how to use equity to buy a property, how much you can actually access, and the mistakes that stall people.
What equity actually is
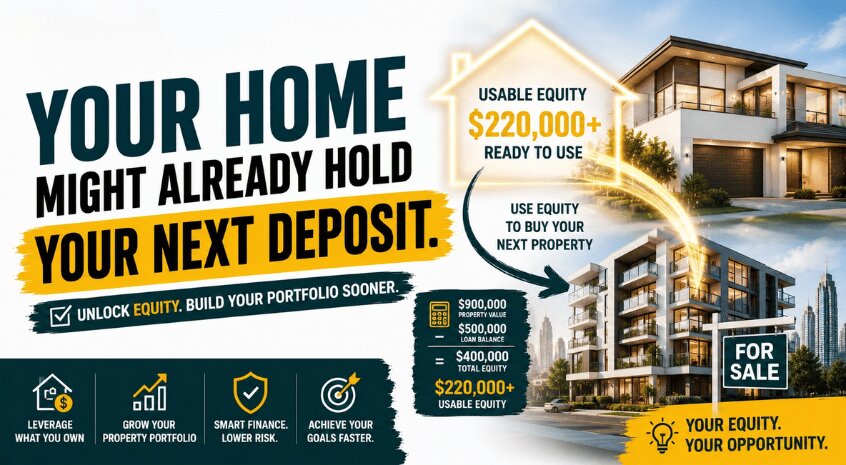
Equity is the difference between your property value and your loan balance. If your home is worth $900,000 and you owe $500,000, you hold $400,000 in equity.
However, banks will not lend against all of it. That distinction matters enormously.
Usable equity is the number that counts
Most lenders let you borrow up to 80% of your property value. So you calculate 80% of the value, then subtract your existing loan.
Using the same example, 80% of $900,000 is $720,000. After subtracting the $500,000 loan, your usable equity is $220,000.
As a result, your real figure is often much smaller than your total equity. Plan around the usable number.
How investors use equity to buy a property
The process is straightforward in principle. To use equity to buy a property, you refinance or set up a separate loan split against your existing home.
That released amount then becomes the deposit for the next purchase. Meanwhile, your original loan continues as it was.
Therefore, you can buy again without draining your savings account. This is how one property quietly becomes three.
What lenders check before approving
- Your current property valuation, which the bank orders itself.
- Your income and job stability.
- Your existing debts, including credit cards and car loans.
- Your capacity to service both loans at a tested higher rate.
Independent explanations of borrowing and refinancing are available on Moneysmart, which is run by the Australian Securities and Investments Commission.
The risk you must respect
Equity is borrowed money, not free money. When you use equity to buy a property again, your total debt rises.
So if values fall, you carry more exposure. If rates rise, you carry higher repayments across two loans.
Consequently, buffers matter even more here. Never release equity right up to the maximum limit.
The mistakes that stall investors
- Releasing equity, then leaving it sitting idle for a year.
- Cross securitising loans, which ties your properties together unnecessarily.
- Buying a weak asset simply because the equity was available.
- Ignoring land tax and cash flow impact across the growing portfolio.
That third mistake is the expensive one. Access to money is not the same as a reason to spend it.
Where the second property should go
Many investors automatically buy again in the same city. That concentrates your risk in one market and one land tax jurisdiction. Instead, consider spreading across markets, as we explain in The Three-Market Formula Behind $1 Billion in Global Investments. Getting the tax structure right matters just as much, which is covered in The Tax Strategy Costing Australians $20,000 Every Single Year.
How to get your property revalued
Your equity position depends entirely on the valuation. So this step decides how much you can actually release.
Lenders order their own valuation, and bank valuations are typically conservative. They often land below what a local agent would quote you.
You can improve the outcome, though. Present recent comparable sales, tidy the property before inspection, and document any renovations you have completed. Consequently, the valuer has evidence to support a stronger figure.
Loan splits keep your tax position clean
This detail matters enormously, yet many people miss it. When you use equity to buy a property, keep the borrowed funds in a separate loan split.
Mixing investment borrowings with your home loan creates a blended debt. As a result, working out which interest is deductible becomes messy and expensive at tax time.
Therefore, set up a clean split from the beginning. Your accountant will thank you every single year afterwards.
How much equity should you use to buy a property?
Just because a lender approves an amount does not mean you should take all of it. Leave yourself room.
- Keep a buffer of several months of repayments untouched.
- Stress test the numbers at a materially higher interest rate.
- Model what happens if the property sits vacant for two months.
- Consider your job security honestly over the next few years.
Investors who use equity to buy a property right up to the limit have no margin for error. Meanwhile, one unexpected event can force a sale at the worst moment.
Timing your equity release
Equity grows in two ways. Values rise, and your loan balance falls.
Rising markets create equity quickly, which tempts people to move fast. However, buying at the top of a cycle with borrowed equity doubles your exposure.
So the better approach is boring but reliable. Release equity when you have found a genuinely good asset, not simply because the equity became available.
A realistic worked sequence
Picture an investor with $220,000 in usable equity. They release $150,000 and keep the remainder as a buffer.
That $150,000 covers a deposit and purchase costs on a $550,000 property. The tenant then covers most of the new loan.
Five years later, both properties have grown. As a result, they can use equity to buy a third, and the cycle continues without new savings.
The problem homeowners keep facing
Thousands of Australians are sitting on substantial usable equity right now and doing nothing with it. They know it exists, yet they do not know the next step.
Meanwhile, inflation quietly erodes the value of that idle position. Waiting feels safe, but it has a cost too.
Equity release versus selling
Some investors sell a property to fund the next one. That approach has a serious hidden cost.
Selling triggers capital gains tax, agent commission, and marketing expenses. Meanwhile, you permanently lose an asset that was still growing.
When you use equity to buy a property instead, you keep the original property and add a second one. As a result, two assets compound rather than one.
What to do if the valuation disappoints
Sometimes the bank valuation comes back lower than you hoped. Do not panic, because you still have options.
- Request a review with supporting comparable sales.
- Approach a different lender, since valuations vary between banks.
- Wait, and let the loan balance reduce further.
- Complete cosmetic improvements that lift the assessed value.
Therefore, one disappointing valuation is rarely the end of the plan. It usually just changes the timing.
Keeping the strategy repeatable
The investors who scale fastest treat this as a system rather than a one off event. They review their position annually and act when conditions suit.
Each time they use equity to buy a property, they reset their buffer before considering the next move. Consequently, the portfolio grows steadily without the stress that forces panic decisions.
Key takeaways
These are the points worth remembering before you contact your lender.
- Usable equity is roughly 80% of value minus your current loan.
- Keep investment borrowings in a separate loan split for clean tax treatment.
- Never release equity right up to the maximum available.
- Avoid cross securitising, because it limits your flexibility later.
- Use equity to buy a property when you find a good asset, not simply because it exists.
Used carefully, equity turns one property into a portfolio. Used carelessly, it doubles your exposure at exactly the wrong time.
Frequently asked questions
How much equity can I actually access?
Most lenders allow borrowing to 80% of your property value, minus your existing loan. That figure is your usable equity, and it is often much smaller than your total equity.
Can I use equity to buy a property overseas?
Many investors do exactly that. You release equity in Australia and use it as the deposit abroad. Lending rules differ by country, so plan the structure carefully.
Will using equity increase my repayments?
Yes. You are borrowing more, so your total repayments rise. The new property’s rent usually covers a large part of that increase.
Should I cross securitise my loans?
Generally no. Keeping loans separate gives you more flexibility later and makes it far easier to sell or refinance one property independently.
How often can I repeat this?
As often as equity, income, and lender policy allow. Experienced investors review annually and rebuild their buffer before each new purchase.
How Grit Global Membership helps
Members get a one on one portfolio strategy review that maps exactly how much equity is usable and where it should go. You also receive private investor deals across three countries and monthly masterclasses.
In short, the equity stops being a number on a bank statement and starts being a plan.
👉 Join the Grit Global Membership and book your free strategy session here
Knowing how to use equity to buy a property is the fastest route to your second one. Just make sure the destination is worth the risk you take to get there.