
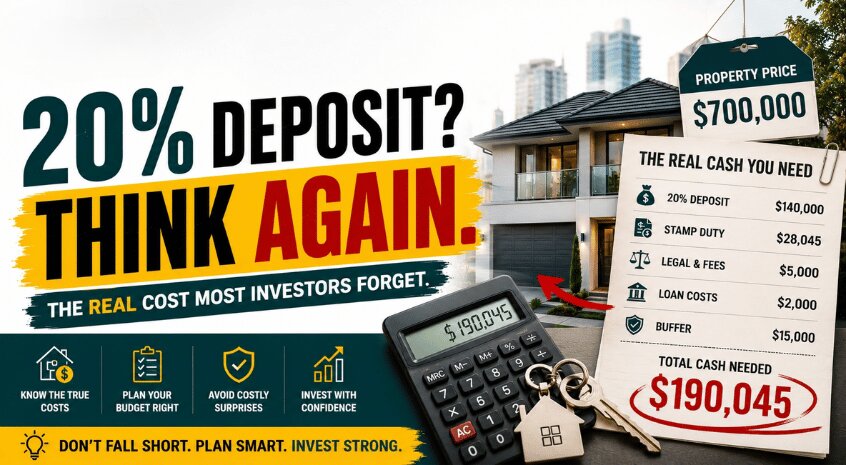
The deposit for an investment property is the single biggest barrier stopping Australians from starting. Most people assume the answer is 20%, and then they get caught short at settlement. This guide breaks down the real cash you need in 2026, including the costs beginners routinely forget.
The short answer
Most lenders want 20% of the purchase price. On a $700,000 property, that means $140,000.
However, that figure is only the deposit itself. It is not the total cash required, and this is where budgets fall apart.
Can you buy with less than 20%?
Yes, in many cases you can. Some lenders accept 10% or 15% for investors.
However, you will usually pay Lenders Mortgage Insurance. That premium protects the bank, not you, and it can add thousands to your loan.
So a smaller deposit gets you in sooner. Meanwhile, it also increases your repayments and your total interest.
The costs people forget
Here is where the real number lives. Budget for all of these before you sign anything.
- Stamp duty, which is often the largest single extra cost.
- Legal and conveyancing fees.
- Building and pest inspections.
- Loan application and valuation fees.
- Landlord insurance and initial council rates.
- A cash buffer for vacancy and repairs.
As a result, the true cash requirement on a $700,000 purchase often sits well above the headline deposit.
Why the buffer matters more than the deposit
New investors obsess over the deposit and ignore the buffer. That is the wrong priority.
Tenants move out. Hot water systems fail. Rates rise. Therefore, a buffer of several months of expenses keeps you calm and in control.
Investors who skip this step get forced into bad decisions later. Selling under pressure destroys more wealth than any deposit gap ever does.
How lenders assess you
Banks look at your income, your existing debts, and your living expenses. They also apply a buffer to test whether you could handle higher rates. Current rate settings and lending conditions are published by the Reserve Bank of Australia, and those settings directly affect how much you can borrow.
Deposit requirements are different overseas
This surprises many Australians. The deposit for an investment property is not a universal rule.
- In Dubai, buyers commonly place around 35% and finance the balance locally.
- In the United States, foreign investors can access up to 75% finance, so roughly 25% down.
- Off plan projects in Dubai often start from just 10% to 20%, paid in instalments.
The American structure surprises people most, because there is no stamp duty and no foreign buyer tax. We walk through it in How Australians Buy Property in the USA.
Do not forget where the deposit comes from
Cash savings are the obvious source. Equity in an existing property is the faster one.
Many investors never touch cash again after their first purchase. Instead, they recycle equity into each new deposit.
How long it takes to save one
Let us be realistic about timelines. Saving a deposit for an investment property on an average income takes years, not months.
Someone saving $1,500 a month reaches $100,000 in a little over five years. Meanwhile, property prices rarely stand still during that period.
This is the frustration behind the whole problem. The target keeps moving while you chase it. Therefore, many investors look at equity or lower entry markets instead of pure cash saving.
Does a bigger deposit always win?
Not necessarily, and this surprises people. A larger deposit reduces your interest and removes mortgage insurance, which is genuinely valuable.
However, waiting three extra years to reach 20% has a cost too. You miss three years of rent and three years of growth.
So the honest answer depends on the market and on your risk tolerance. Sometimes paying insurance to start earlier is the better commercial decision.
Where your deposit money should sit
- Keep it liquid, because settlement dates do not wait.
- Avoid volatile assets in the twelve months before purchase.
- Use an offset account if you already hold a home loan.
- Keep the buffer separate from the deposit, not blended together.
That last point protects you. Once the buffer gets absorbed into the deposit, you settle with nothing left for the first surprise.
Guarantor and family assistance options
Some investors use a family guarantee to avoid mortgage insurance. A parent offers equity in their property as additional security.
This can work well, but it carries real risk for the guarantor. Consequently, everyone involved should get independent legal advice before proceeding.
Planning your deposit around your goal
Your deposit for an investment property should match the strategy, not just the bank minimum. Growth focused purchases and cash flow focused purchases behave very differently.
For example, a higher deposit on a cash flow property produces positive income sooner. Meanwhile, a lower deposit on a growth property gives you more leverage in a rising market.
So decide what the property is for first. Then size the deposit for an investment property to suit that job.
The problem most first time investors have
They save hard for years, then buy the wrong property because they are exhausted and impatient. All that discipline goes into an asset nobody researched properly.
Consequently, the deposit was never really the problem. The decision that followed it was.
Deposit size and your borrowing power
Your deposit for an investment property interacts directly with your borrowing capacity. Both must work together.
A larger deposit reduces the loan you need, so servicing becomes easier. Meanwhile, a smaller deposit stretches your income assessment further.
Therefore, calculate both numbers before you shop. Knowing your maximum price prevents wasted weekends inspecting properties you cannot fund.
Common deposit mistakes
- Counting the buffer as part of the deposit.
- Forgetting stamp duty entirely in the early budget.
- Assuming a gift from family needs no documentation.
- Taking on a car loan during the application process.
That last mistake is remarkably common. New debt taken weeks before settlement can reduce your approval and cost you the purchase.
Should you buy sooner with a smaller deposit?
There is no universal answer, but there is a useful test. Compare the cost of mortgage insurance against the likely growth and rent you forgo by waiting.
In a flat market, waiting and saving more often wins. In a rising market, entering earlier with a smaller deposit for an investment property frequently wins instead.
So the decision is commercial, not moral. Run the numbers for your actual market rather than following general advice.
Key takeaways
Here is what to carry forward from all of this.
- Plan for 20%, but expect the real cash requirement to be higher.
- Stamp duty and purchase costs sit on top of the deposit, never inside it.
- Keep your buffer separate and untouched through settlement.
- Equity can replace savings once you own your first property.
- Deposit requirements differ sharply between Australia, Dubai, and the United States.
Finally, remember that saving the deposit is the easy part. Choosing the right asset is the decision that actually builds wealth.
Frequently asked questions
What is the minimum deposit for an investment property in Australia?
Most lenders prefer 20%. Some accept 10% or 15%, although you will usually pay Lenders Mortgage Insurance on the smaller amount.
Does the deposit for an investment property include stamp duty?
No, and this catches people out constantly. Stamp duty, legal fees, and inspections all sit on top of the deposit, so budget for them separately.
Can I use my superannuation as a deposit?
Not directly from a standard super account. However, a self managed super fund can purchase property under strict rules, so seek specialist advice first.
Is it better to wait and save a bigger deposit?
It depends on your market. In a rising market, entering earlier often beats waiting. In a flat market, saving more and avoiding insurance usually wins.
How much buffer should I keep after settlement?
Aim for at least three to six months of loan repayments and expenses. That buffer protects you through vacancies, repairs, and rate movements.
How Grit Global Membership helps
Membership gives you a one on one portfolio strategy review before you commit your deposit. You also receive private investor deals across Australia, Dubai, and the United States, plus monthly masterclasses if your goal is to clear your own home loan faster; read How to Pay Off Your Australian Mortgage in 10 Years alongside this guide.
👉 Join the Grit Global Membership and book your free strategy session here
Save for the deposit, absolutely. Just make sure the property you buy with it deserves the effort.