
Currency & Exchange Rate Risk for Australian Investors
What every global property investor needs to know — and the strategies that manage it without overcomplicating the portfolio.
GRIT Property Group
Melbourne · Dubai · New York
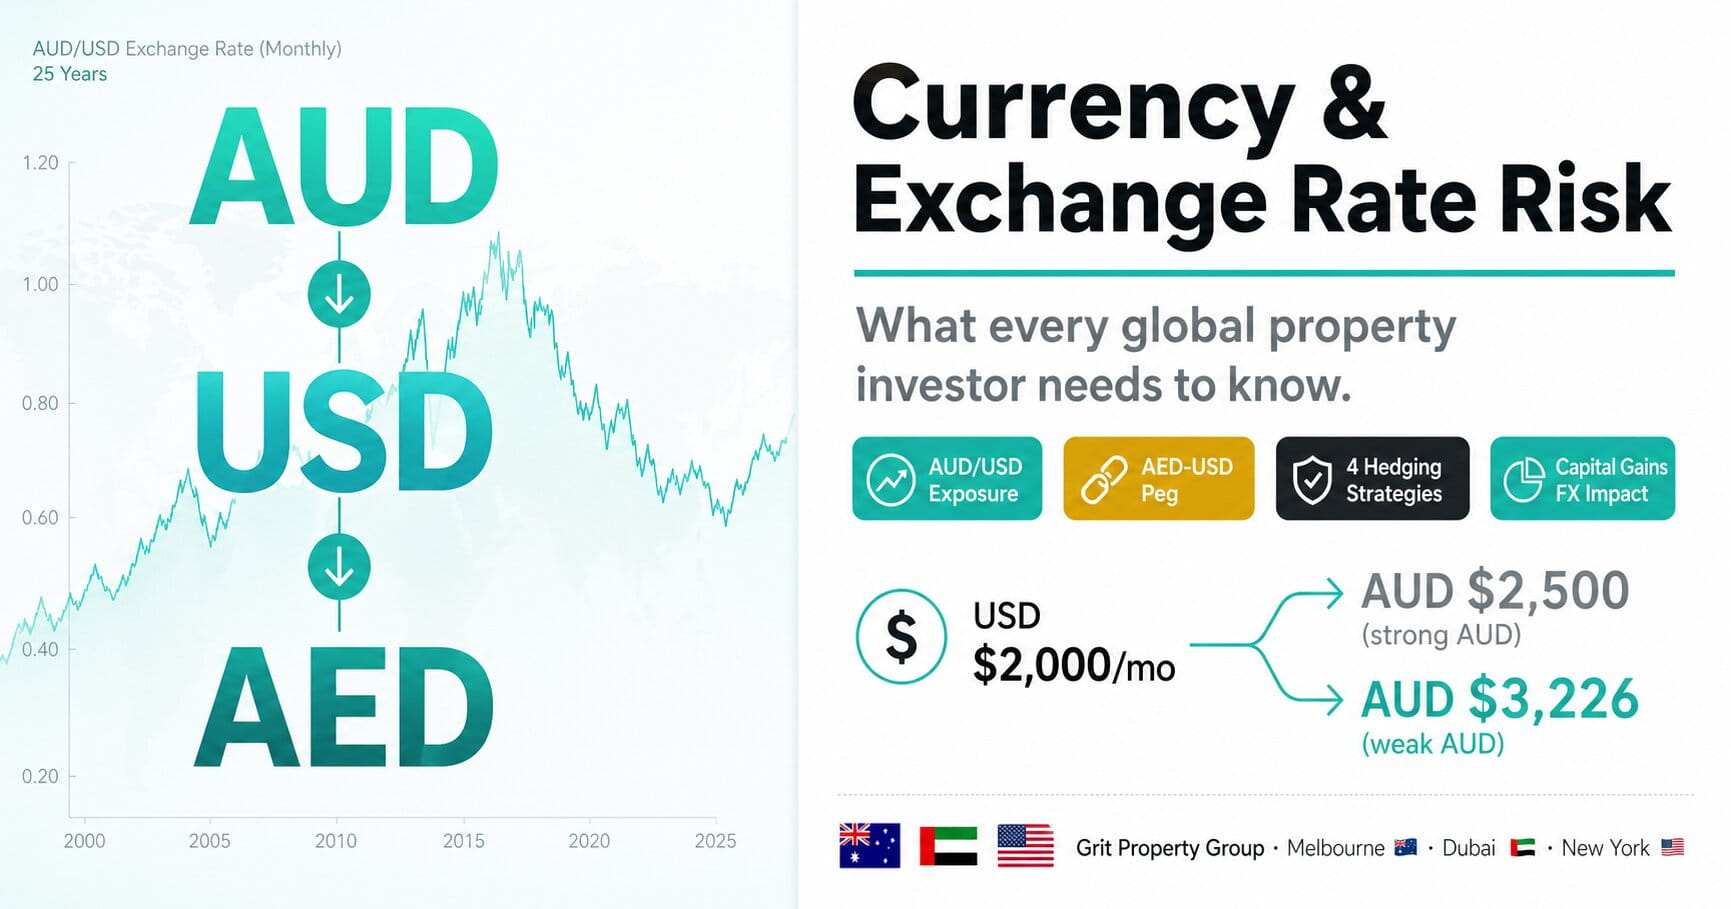
Currency risk is real. It is also manageable — and for Australian investors in the right markets, it can actually work in your favour.
The moment you buy a property in a currency other than AUD, you have taken a currency position. Your Dubai apartment generates AED. Your US rental generates USD. When you convert those returns to Australian dollars — which is how most investors ultimately measure their wealth — the exchange rate determines what you actually receive.
This is not a reason to avoid international markets. It is a reason to understand what you are exposed to, which risks are manageable, which are not, and how the three GRIT markets interact with the Australian dollar in ways that can strengthen a portfolio rather than weaken it.
The basics — how currency affects your return
A property generating USD $2,000 per month in net rental income converts to Australian dollars at whatever the AUD/USD rate is at the time of conversion.
| AUD/USD rate | USD $2,000 converts to | Monthly difference |
|---|---|---|
| 0.80 (AUD strong) | AUD $2,500 | Baseline |
| 0.72 (AUD moderate) | AUD $2,778 | +AUD $278 |
| 0.62 (AUD weak) | AUD $3,226 | +AUD $726 |
| 0.55 (AUD very weak) | AUD $3,636 | +AUD $1,136 |
The critical insight: The Australian dollar is a commodity currency — it weakens when global risk sentiment deteriorates, when iron ore prices fall, and when the economy slows. These are precisely the conditions under which Australian property also tends to soften. A weak AUD simultaneously boosts your USD rental income and cushions your Australian portfolio. This is a structural correlation that makes USD income a natural hedge.
The three GRIT markets — currency profile
| Market | Currency | AUD exposure | Volatility | Key drivers |
|---|---|---|---|---|
| 🇦🇺 Australia | AUD | None — home currency | N/A | RBA cash rate, commodity prices, global risk sentiment |
| 🇦🇪 Dubai | AED | AED/AUD | Low–moderate | AED is USD-pegged since 1997; mirrors USD/AUD |
| 🇺🇸 United States | USD | USD/AUD | Moderate | US Fed funds rate, economic data, global risk-off sentiment |
The AED-USD peg: The UAE Dirham has been pegged to the US Dollar at 3.6725 AED per USD since 1997 — through the 2008 GFC, the 2015 oil shock, and the 2020 pandemic. For Australian investors, AED and USD exposure are effectively the same currency risk, not two separate exposures.
How the AUD behaves — and what it means for your returns
The Australian dollar has traded between USD 0.48 and USD 1.10 over the past 25 years — one of the most volatile developed market currencies.
| Period | AUD/USD | Impact on USD/AED income |
|---|---|---|
| 2001 (AUD low) | ~0.48 | Maximum AUD value — USD income at peak |
| 2011 (AUD parity) | ~1.04 | Minimum AUD value — USD income at trough |
| 2015–2016 | ~0.68–0.72 | Moderate premium to AUD |
| 2020 (COVID low) | ~0.57 | Significant premium — natural hedge in action |
| 2024 | ~0.63–0.66 | Meaningful premium — below 30-year average |
The long-run average: Over 30 years, AUD has averaged approximately USD 0.73. The current rate (~0.63–0.66) means Australian investors converting USD income today are receiving more AUD per dollar than the long-run norm.
Currency risk strategies — practical options
Currency and capital gains — the often-overlooked issue
When you sell an overseas property, the ATO treats the capital gain in AUD terms — not in the foreign currency. This creates an additional currency dimension most investors don't anticipate.
| US property purchased for USD $350,000 (at AUD/USD 0.66) | Cost base: AUD $530,000 |
| US property sold for USD $480,000 (at AUD/USD 0.60) | Proceeds: AUD $800,000 |
| Capital gain (AUD) — what you pay CGT on | AUD $270,000 |
| Capital gain in USD | USD $130,000 (AUD $217,000) |
The AUD capital gain is larger than the USD gain because AUD weakened between purchase and sale. The reverse is also true — if AUD strengthens, your AUD gain can be smaller. This is a reason to model currency scenarios at purchase, particularly for shorter hold periods.
Practical currency management for GRIT clients
| Task | Recommended approach |
|---|---|
| Transferring AUD for purchase deposit | Use a specialist FX provider (OFX, Wise, or broker-referred) — not your bank. Rate difference on a $200K transfer: typically $2,000–$5,000 |
| Receiving monthly rental income | Hold in local bank account (US LLC or UAE account) and convert monthly, quarterly, or annually based on cashflow needs |
| Planning for US property sale | Engage a cross-border accountant 12+ months before anticipated sale to model AUD capital gain under different currency scenarios |
| Currency forward contracts | Only if you have a specific AUD requirement and a fixed timeframe — seek specialist FX advice |
Get your currency exposure modelled before you invest
A GRIT Discovery Session includes a cashflow model in both AUD and the investment currency — so you can see the range of outcomes under different exchange rate scenarios before you commit.
Book Free Discovery Session →"The truth will set you free."
GRIT Property Group │ Melbourne · Dubai · New York